

Get Paid Early: Cash Advance
StreamFunds, Inc.
- 4.2
- 163.00 Reviews
- 50.00K
- Downloads
- Free
- Price
Screenshots
Get Paid Early: Cash Advance Pros and Cons
Pros
- Fast access to part of your earned wages before payday.
- Simple application process with minimal paperwork.
- Useful for covering unexpected short-term expenses.
- Repayment is generally aligned with your regular payday.
- Clear balance tracking helps monitor advances and repayments.
Cons
- Fees may vary depending on the advance amount and delivery speed.
- Eligibility can depend on employer and payroll participation.
- Frequent advances may make future paychecks feel smaller.
- Some features may require identity and income verification.
- Availability and terms can differ by state or region.
 Analysis by All-app
When an unexpected bill arrives before payday, the problem is often timing rather than income. That is the situation I had in mind while trying Get Paid Early: Cash Advance, a finance app from StreamFunds, Inc. Its purpose is straightforward: help eligible users access pay they have already earned before the normal payday, without presenting the service as a traditional loan. I found the idea useful for short gaps, but I also came away with a clear warning: early access to wages can smooth one difficult week, yet it does not replace a workable monthly budget.
The app is free to install and is rated for Everyone, which makes the first impression approachable. It has an average rating of 4.2 from around 700 ratings, and its audience has already taken it beyond a small test group, with over 50,000 installs. Those figures suggest that people are finding a practical use for it, although they do not tell me whether every user will qualify or whether every employer and payroll setup will work equally well.
From a cash shortfall to an earlier payday
I find the most useful way to judge this section is to separate a genuine timing gap from a shortage that will still be there next month. That distinction helps me decide whether accessing earned wages is a sensible bridge or just a temporary patch, and it sets up a closer look at how the request and payday fit together.
Starting with the reason for using it
The best way to understand this app is to begin with a specific situation. Imagine that I have worked enough hours to cover an upcoming expense, but my regular payday is still several days away. I do not want to put the bill on a credit card, take out a conventional loan, or pay interest simply because my wages are arriving later. In that case, an earned-pay access service can be more sensible than borrowing against future income.
That distinction matters. I would not open this app expecting a general-purpose personal loan, a budgeting suite, or a way to create extra money. The useful starting question is, “Have I already earned the pay I need, and am I only waiting for the payroll schedule?” If the answer is no, this is probably the wrong tool. If the answer is yes, the app’s central idea is much easier to evaluate.
I also recommend deciding the exact amount needed before opening the app. A smaller withdrawal tied to a specific bill is easier to manage than taking the maximum amount simply because it appears available. My practical rule would be to use it for a defined necessity, such as a transport cost, utility payment, or grocery gap, rather than for flexible spending that can quietly expand.
Setting up the first request
The initial flow is built around connecting the service to the information needed to identify earned pay and deliver funds. This is the point where patience matters. Financial apps cannot make a useful decision without the right account, employment, or payroll context, so I would have the relevant details ready and read each screen instead of tapping through automatically.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
One of the less obvious strengths of this kind of workflow is that it separates earned wages from a conventional credit application. I am not approaching the process by presenting a long-term repayment plan or asking for a loan amount based only on a credit profile. The important question is connected to work already completed. That makes the service potentially more comfortable for someone who wants to avoid adding a standard loan to their financial history.
At the same time, I would not confuse a simple concept with a frictionless setup. The experience depends on the app being able to recognize the employment and payroll information it needs. If that connection is incomplete, outdated, or arranged through a payroll system the service cannot work with smoothly, the process may stop before the useful part begins. That is not a reason to dismiss the app, but it is a reason to avoid relying on it as the only plan for an urgent payment.
Checking what is actually available
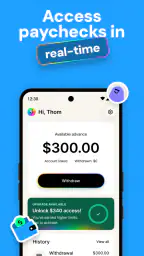
Once the relevant information is in place, the next step is to review the amount the app makes available. This is where I would slow down and treat the displayed figure as a limit for the current situation, not as a recommendation. The amount I can access may be less important than the amount I can safely use without making the next payday harder.
A good workflow is to compare the available amount with the bill that caused the problem. If the bill is smaller, I would request only what closes that gap. If the bill is larger, I would not automatically stack other borrowing on top. Instead, I would look for a payment arrangement, a lower-cost alternative, or a way to delay a nonessential purchase. The app can address a timing mismatch; it cannot make an unaffordable expense affordable.
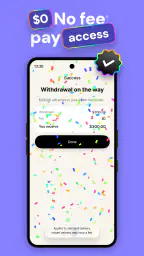
This is also the moment to inspect the final terms shown inside the request flow, especially how and when the money will arrive and how the earned pay will be handled later. The appeal of “no loans, no interest, and no hidden fees” is clear, but responsible use still means reading the confirmation screen carefully. A free app does not mean every financial decision made through it is automatically risk-free.
Moving from approval to delivery
The handoff from an approved request to receiving funds is the part most users care about. In my view, the app’s value is measured less by how polished the opening screens feel and more by whether the money reaches the right destination in time for the real-world need. I would therefore submit a request before the last possible moment, not while standing at a checkout or waiting for a bill to become overdue.
That timing habit is important because several parties may sit between the request and the result: the app, the connected payroll information, and the destination used to receive the funds. Even when the service is designed for early access, a user should leave room for processing or account-related friction. I would keep a backup payment method available until the transfer is visibly complete rather than assuming that an on-screen request immediately equals spendable cash.
This is one of the practical insights I would want a friend to know. The app may solve the “earned but not yet paid” problem, but it does not remove the need to coordinate the final payment. If I am using the money for rent, a utility account, or a scheduled debit, I still need to confirm that the receiving side accepts the funds and that the timing lines up. The handoff is part of the workflow, not an administrative detail after the app has done its job.
What happens to the next payday
The outcome is easiest to judge by looking beyond the immediate relief. Accessing earned pay early means the regular payday may contain less of the wages I was expecting, because part of that income has already been made available. I would write down the amount used and the expense it covered, then check the next pay cycle with that earlier access in mind.
This simple recordkeeping step is more valuable than it sounds. Without it, early access can feel like extra money, especially when the original bill is no longer visible in the account. With it, I can see that the app moved the timing of my income rather than increasing it. That makes the service easier to use deliberately and helps prevent a repeating pattern in which each pay period starts by covering the previous one.
For a worker with predictable hours, a stable payroll routine, and a one-off timing problem, this can be a reasonable bridge. I can imagine using it when a necessary expense lands just before payday and I know the corresponding wages are already earned. I would be much more cautious if my hours changed often, my income was already committed to recurring bills, or I needed early access every pay cycle just to stay current.
A realistic everyday scenario
Here is the kind of situation where I think the app makes the most sense. I have completed my scheduled work, my normal payday is approaching, and my car needs an essential repair before I can get to work again. I open the app, review the amount connected to earned pay, request only the portion needed for the repair, and keep the remaining money in my normal payday plan. After the transfer arrives, I pay the repair bill and note that the next paycheck will be smaller by the amount already accessed.
The important part of that scenario is not the repair itself. It is the chain of decisions: the expense is necessary, the wages have already been earned, the request is limited, and the next payday is planned in advance. If any of those conditions changes, the same action becomes less attractive. For example, using early pay for an impulse purchase gives me no lasting benefit, while using it to cover a recurring shortfall may simply postpone the same problem.
How it compares with familiar alternatives
Compared with a credit card, early wage access can be appealing because it is tied to pay already earned rather than revolving credit. A credit card remains more flexible for larger purchases or emergencies that do not line up with payroll, but that flexibility can become expensive if a balance carries forward. I would choose the app for a narrow payday-timing gap and a card only when I understand the repayment cost and genuinely need the broader payment option.
Compared with a traditional personal loan, this service is more focused and less suitable for a large, planned expense. A loan may provide a structured repayment schedule and a larger amount, but it also creates a longer obligation. If the need is a short wait for wages, taking out a loan would feel disproportionate to me. If the need is a major repair, medical bill, or debt consolidation, I would compare formal credit options instead of assuming an earned-pay tool can handle it.
Compared with asking an employer for a payroll adjustment, the app may be more convenient when the employer’s normal process is slow or unavailable. On the other hand, an employer advance or payroll change could be easier for some workers because it keeps the arrangement inside the workplace. I would compare the effort, timing, and effect on the next paycheck rather than treating one method as universally superior.
Compared with overdraft protection, the app is better suited to planning ahead for a known gap. An overdraft is often a reaction after an account has already fallen short, while early access can be arranged around an expected expense. Still, overdraft protection may cover a transaction automatically when timing is unpredictable. I would not use either option casually; the best choice depends on whether I can identify the expense before it happens.
Where the flow can break
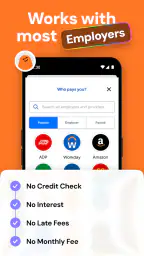
The first possible break is eligibility or account connection. The app’s promise is meaningful only when it can identify earned pay through the user’s particular work and payroll arrangement. A person with irregular freelance income, cash payments, multiple employers, or a recently changed job may find that the normal path does not match their situation. I would not recommend building an emergency plan around an app until I had completed the setup and understood how my own pay pattern appears.
The second break is timing. “Early” does not mean “instant in every practical circumstance.” A request made late, a destination account that needs additional processing, or a payroll update that has not appeared can all create a gap between requesting money and using it. My workaround would be to apply during normal planning hours, keep confirmation details, and preserve a backup route for any bill with a strict deadline.
The third break is behavioral rather than technical. The service can make it easy to solve today’s problem without confronting next week’s reduced paycheck. I would set a personal limit: use it for a specific earned-income mismatch, not as a standing supplement. If I find myself opening the app before every payday, that is a sign that I need a broader change to expenses, income, or bill timing.
There is also a privacy and trust decision whenever a finance app needs access to employment or payment information. I would review the permissions and explanations shown during setup, use a secure device, and avoid sharing account credentials through unofficial messages. StreamFunds, Inc. is the developer behind the app, but the responsibility to understand what I am authorizing still belongs to me. Convenience should not replace basic care with financial accounts.
Who will appreciate it most
I see the strongest fit for employees with regular pay, a predictable next payday, and an occasional expense that arrives slightly too soon. It may also suit someone who wants to avoid interest-bearing borrowing for a small, clearly defined need and who can remember that early access changes the timing of income rather than increasing it.
I would be more hesitant to recommend it to someone with unstable hours, several overdue obligations, or no room in the next paycheck. It is also not the right answer for a large purchase, a long-term debt problem, or an expense that will recur every month. In those cases, a conversation with an employer, a nonprofit financial counselor, a structured payment plan, or a carefully compared credit product may be more appropriate.
Device details and day-to-day impression
The current release is version 3.0.35, and it supports devices running Android 7.0 or newer. That gives the app a fairly broad reach for Android users, including people who do not own a recent phone. I still recommend keeping the operating system updated where possible, particularly because a finance app handles information that deserves a secure environment.
As a free finance app, it is easy to try without paying an upfront purchase price. The age rating of Everyone also reflects a broadly accessible presentation, but age suitability should not be confused with financial suitability. A younger or inexperienced user may still need an adult’s guidance when deciding whether accessing wages early will make the following payday difficult.
After working through the complete path, my opinion is positive but deliberately limited. The real benefit is control over timing, not additional income. When I use that distinction to guide the decision, the app feels focused and potentially helpful. When I ignore it, the same convenience could encourage a cycle of repeated early withdrawals.
I would recommend Get Paid Early: Cash Advance to a friend who has already earned the money, needs it for a specific short-term expense, and can plan around the next payday. I would tell that friend to complete the setup before an emergency, request only the necessary amount, allow time for the handoff, and record the effect on upcoming pay. For anyone seeking a loan, a full budgeting platform, or a permanent answer to insufficient income, I would point elsewhere. Used as a careful bridge, it has a clear purpose; used as a substitute for financial planning, it is much less convincing.
Frequently Asked Questions
What is Get Paid Early: Cash Advance, and how does it work?
Get Paid Early: Cash Advance is a financial app designed to help eligible users access part of their expected paycheck before their regular payday. After creating an account, you may be asked to connect employment, income, or bank information so the service can evaluate eligibility. If approved, available funds and repayment terms are shown before you confirm a cash advance. Availability, limits, and processing times can vary by user.
How much money can I borrow through Get Paid Early: Cash Advance?
The amount available through Get Paid Early: Cash Advance depends on several factors, including your income, employment information, account history, repayment behavior, and the provider’s eligibility rules. New users may receive a smaller limit, while eligible returning users could qualify for more. The app should display the exact advance amount, any applicable fees, and the expected repayment date before you accept the transaction.
Are there fees or interest charges for using the app?
Before requesting an advance, carefully review the cost breakdown shown in the app. Depending on the product and your location, charges may include an optional expedited-transfer fee, a subscription or membership fee, or other service costs. A cash advance may not use traditional interest, but that does not necessarily mean it is free. Always check the final agreement and repayment amount before proceeding.
When will I receive the cash advance, and how is it repaid?
Delivery time depends on the transfer option you select and the financial institutions involved. Standard transfers may take longer, while an expedited option could arrive sooner if it is available and carries an additional fee. Repayment is generally scheduled for your next payday or another date stated in the agreement. Make sure sufficient funds are available to avoid failed payments, bank fees, or account restrictions.
Is Get Paid Early: Cash Advance safe, and who should use it?
The app may be useful for eligible users facing a short-term cash-flow problem, but it should not replace regular budgeting or long-term financial planning. Before signing up, review its privacy policy, permissions, fees, repayment conditions, and customer-support information. Only provide accurate financial details through the official app, and avoid borrowing more than you can comfortably repay on the scheduled date.


